
Beginners Guide to Starting a College Fund for Your Child
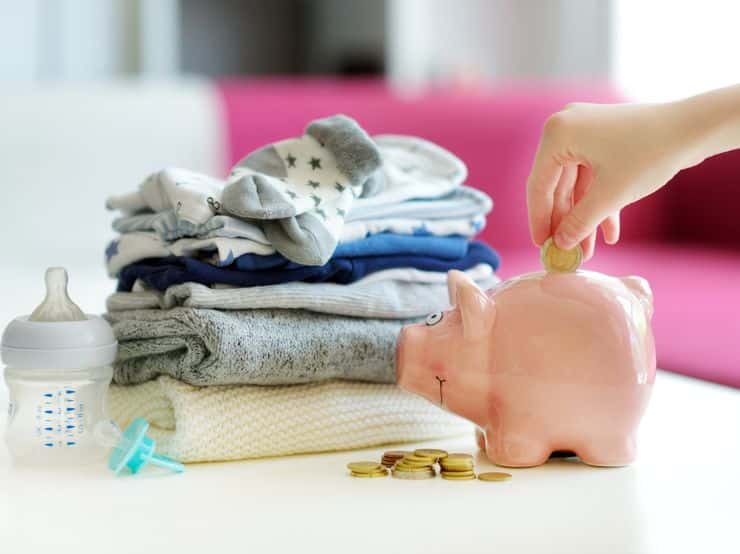
Thinking about college already? I know, it seems way off when your little one’s still in diapers. But starting a college fund now is a smart move!
College isn’t getting any cheaper, and starting early means you’re giving your child a head start. Don’t worry if this is all new to you – let’s break it down together.
Why Start Now?

So, why should you start now? Simple. The earlier you start, the more time your money has to grow. Even if it’s just a little bit here and there; it all adds up.
Think of it like planting a tiny seed that, over the years, grows into a sturdy tree. Plus, it feels good knowing you’re preparing for your child’s future.
Your Options for Saving:
Okay, so how do you actually start saving? There are a few options, and you don’t have to be a financial guru to figure it out.
1. 529 College Savings Plan
This is a popular one. A 529 plan is basically a savings plan that gives you tax benefits if you use the money for education. You can pick where to invest the money, and it grows tax-free.
Later, when it’s time for college, you can use it for tuition, books, and even room and board. The nice thing? You can start small and just add what you can, when you can.
2. Coverdell ESA
Another option is the Coverdell Education Savings Account (ESA). It’s similar to a 529 but with a few differences. For one, there’s a lower limit on how much you can contribute. But the upside? More investment choices and the ability to use the funds for K-12 expenses, not just college.
3. Regular Savings Account
Not ready to commit to a specific college savings plan? No worries. You can start with a regular savings account. It’s flexible, and you can always move the money to a 529 or something else later. Just remember, you won’t get the tax perks that come with the other options.
4. Custodial Accounts (UGMA/UTMA)
There are also custodial accounts – like UGMA or UTMA. These accounts are in your child’s name, but you’re in control until they reach a certain age. The money can be used for college or anything else that benefits your child. Just keep in mind that it might impact financial aid later on.
How Much Should You Save?
Here’s where it gets tricky – how much should you save? The answer really depends. Obviously, the more kids you have, the more you’ll want to put aside.
Start with what you can afford, even if it’s just a little. Every bit helps. Maybe you want to cover all college costs, or maybe just give them a head start. There’s no right or wrong answer here.
A good rule of thumb? Start with small, manageable amounts and increase as you can. Even $25 a month can make a difference over time. And don’t stress – online calculators can help you figure out how much you might need based on your goals and your child’s age.
Getting Family Involved
You don’t have to do this alone. If grandparents or other family members want to chip in, let them. Many 529 plans allow for gift contributions so loved ones can add to the fund. It’s a great way to turn holiday or birthday gifts into something meaningful.
Staying Consistent
The key to saving for college is to be consistent. Set up automatic contributions if you can. It’s easier when you don’t have to think about it. Check-in on your plan every so often, and if you can, consider increasing your savings as things change. And remember, it’s okay if you’re starting small. It all adds up.
The Bottom Line

Starting a college fund might feel like a big deal, but it’s one of those things that will pay off in the long run. By starting now and saving a little at a time, you’re giving your child a great gift – a head start on their future.
Whether you go with a 529, a savings account, or something else, the important thing is that you’re doing it. Every dollar saved is one less they’ll have to worry about later!